Reimagining Revenue Systems Ideas Showcase
Where Are They Now?
Six-month updates from six featured innovations
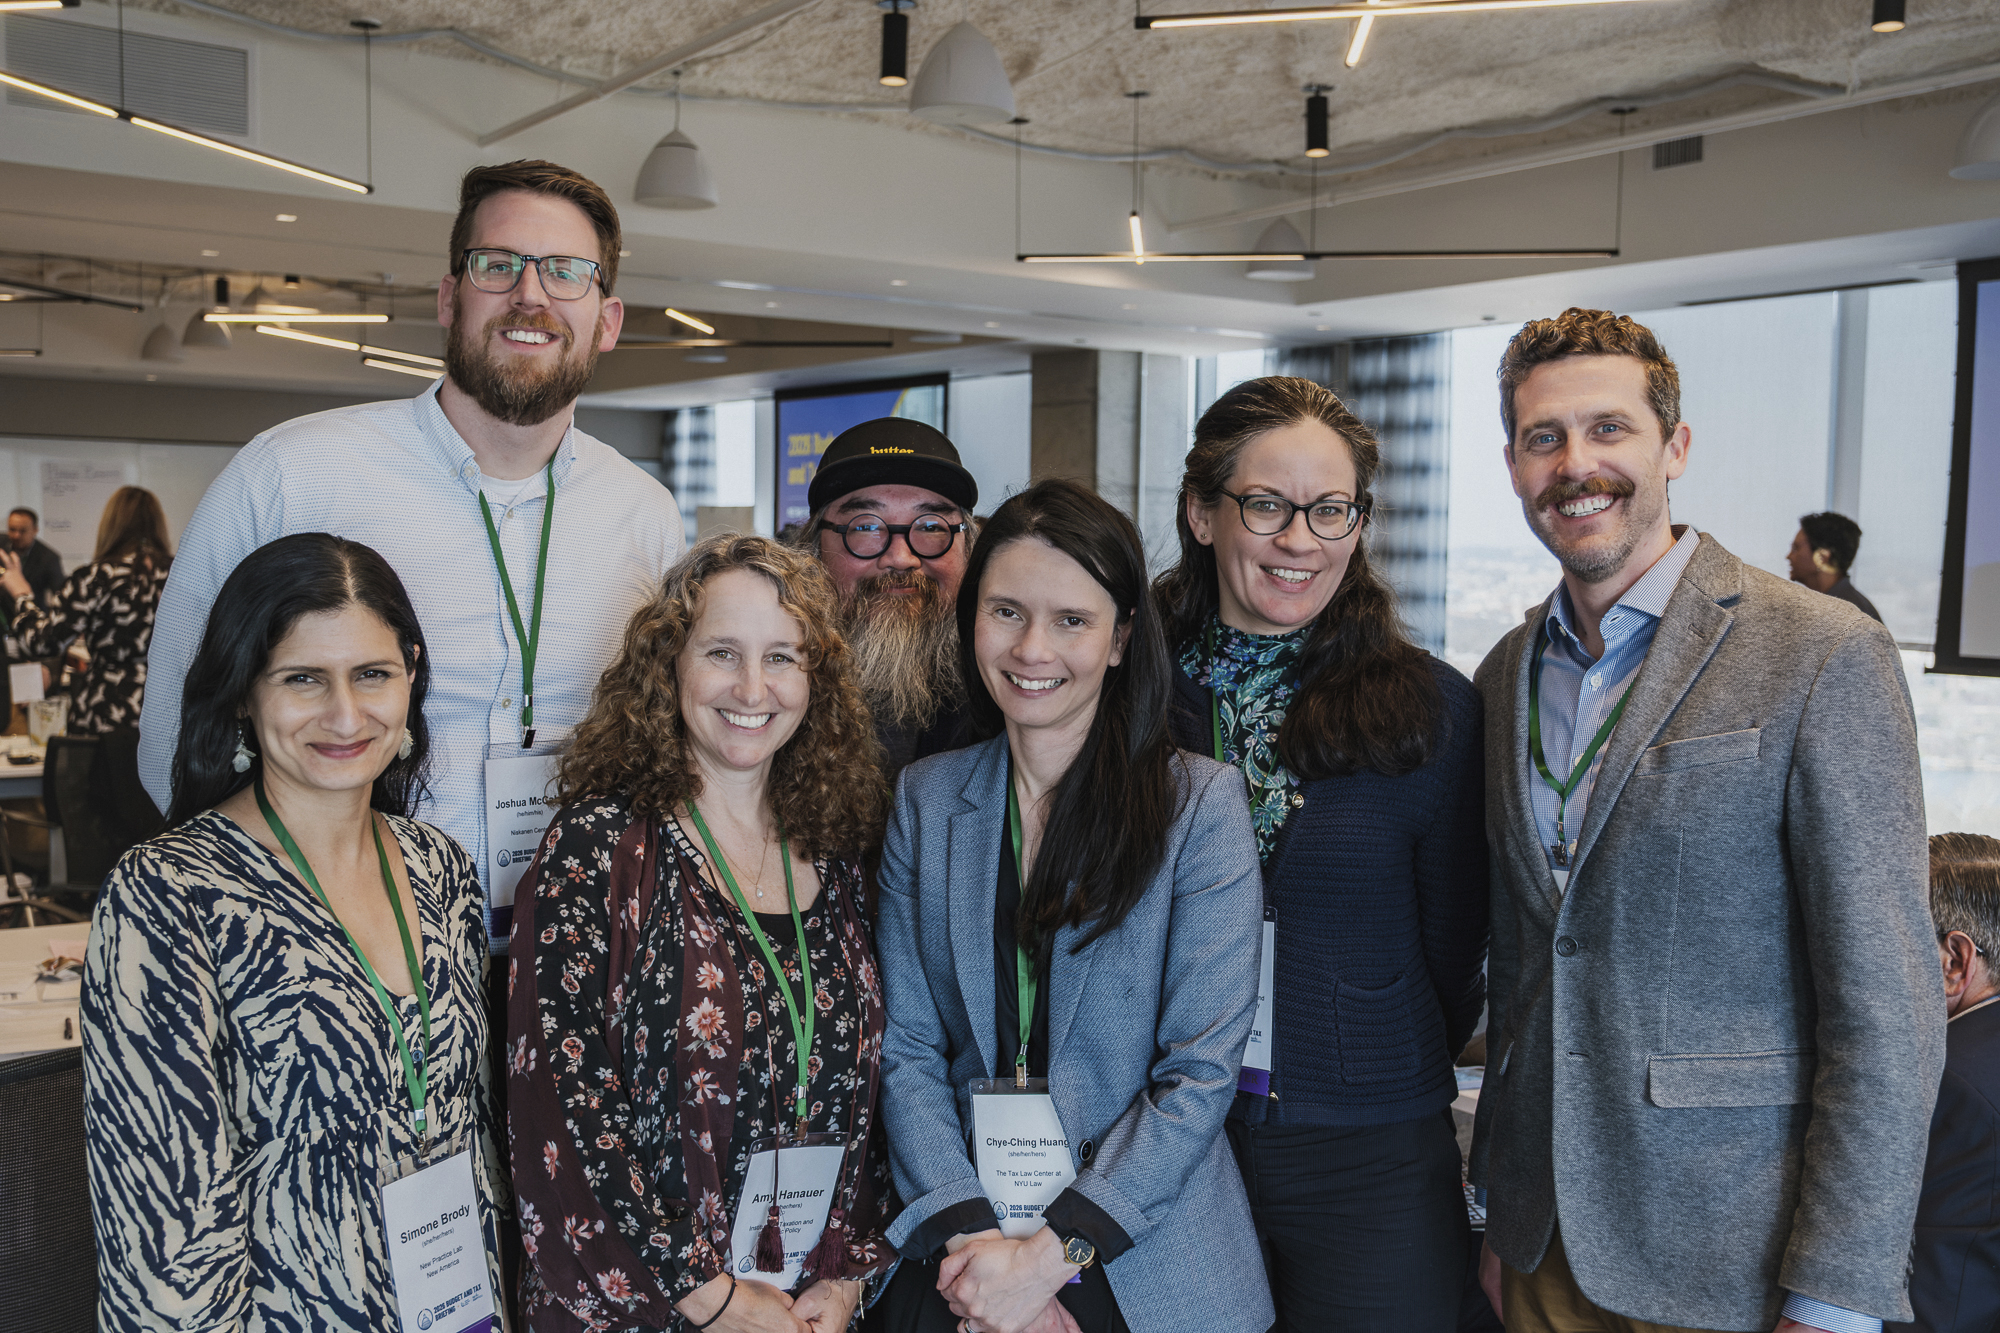
In March 2026, Economic Opportunity Funders and the Tax Equity Funders Network hosted an Ideas Showcase featuring six forward-looking approaches for creating more equitable, effective, and sustainable revenue systems.
Six months later, we checked back with the featured organizations to learn what has changed, what they are learning, and what comes next.
Explore the original Reimagining Revenue Systems Ideas Showcase Overview and Recap for presentation materials, key takeaways, and related resources.
Explore the Updates
- FACT Coalition
Using transparency to deter multinational corporate tax evasion and avoidance. - Institute on Taxation and Economic Policy
Enacting state wealth proceeds taxes. - New Practice Lab at New America
Automatically returning money owed to families missing out on tax credits. - Niskanen Center
Reviving America’s contributory tradition by expanding payroll taxes as a foundation for public benefits. - The Tax Law Center at NYU Law
Remaking federal tax administration. - Washington Center for Equitable Growth
Reclassifying large passthrough businesses to strengthen equitable revenue systems.
Looking Ahead
Six months after the Showcase, these innovations are generating new evidence, shaping public debate, and attracting interest from policymakers and advocates. Some are moving toward legislation or implementation, while others are building the policy frameworks, coalitions, and public understanding required to enable future change.
Continued philanthropic support can help organizations respond to growing state and federal opportunities, deepen research and policy development, strengthen communications and coalition-building, and translate promising ideas into action.
FACT Coalition
Using transparency to deter multinational corporate tax evasion and avoidance.
About the Innovation
Starting in 2026, improved US accounting rules and transparency laws in Europe and Australia will require American corporations to publicly report new data about how much tax they pay and in which countries, creating opportunities to combat corporate tax dodging that has cost the US trillions in unpaid taxes. Evidence from Europe shows such disclosures increase government revenues through a deterrent effect, and the new data will enable investors, labor unions, tax advocates, and journalists to scrutinize corporate tax practices and build pressure for reform in the US. The FACT Coalition will analyze this new data to educate policymakers and build coalitions across diverse stakeholders to close loopholes and reform corporate tax laws.
Six-Month Update
We are delivering on our commitment to hold corporations accountable for their tax dodging by making full use of new corporate tax disclosures. Our careful analysis uncovered billions of dollars in taxes avoided by major corporations routing profits through tax havens, sparking a major story in the New York Times, with our work also featured and quoted in the Wall Street Journal and the Financial Times (below). We testified on our findings on pharma and big oil companies in a shadow hearing convened by the Congressional Progressive Caucus.
We are developing two new areas of focus:
- Taxing AI companies: We’re building on our deep expertise in Big Tech tax issues, and working in tandem with our labor and other member organizations.
- Defending democracy: Corporate tax accountability and financial transparency are essential to a robust democracy that delivers for ordinary people. On September 22, we’re hosting a hybrid event with leading voices in tax and anticorruption, titled “From Hidden Wealth to Public Trust – Reclaiming Our Democracy”, open to all.
On the organizational front, we have completed a leadership transition: after outgoing executive director Ian Gary retired, a new all-female co-leadership team — Erica Hanichak and Zorka Milin — took the reins on July 1.
Learn More
- Event: From Hidden Wealth to Public Trust
- Testimony: Prepared Testimony for Shadow Hearing: “Visions of an Affordable Life: Taxing Corporate Greed”
- Op-Ed: Global Corporate Tax Reform and the AI Economy
Contact
For more information, contact Zorka Milin, Policy Director, zmilin@thefactcoalition.org.
Institute on Taxation and Economic Policy
Enacting state wealth proceeds taxes.
About the Innovation
ITEP has developed a policy framework for a state-level Wealth Proceeds Tax based on a new Minnesota law that raises significant revenue from very wealthy families by applying a tax to the proceeds generated by owning wealth. Simplicity in administering, along with the promise of increased parity in the treatment of earned and passive income, makes this an attractive option for states. ITEP and its partners are working to popularize the idea, with organizations in at least nine states expressing interest in advancing the solution.
Six-Month Update
Partners moved state wealth proceeds taxes, with significant traction in six places.
- In Pennsylvania, partners asked us to model legislation for 2027.
- In Oregon, a tax commission is considering regressive tax changes and partners will elevate this as an alternative in 2027.
- ITEP presented to both Vermont’s tax and budget committees, another ITEP priority bill advanced, and this idea will be more viable next year than this.
- Minnesota lawmakers introduced a similar bill last year and partners will encourage reintroduction with a tweak to better align with our proposal.
- Maine partners will include it in a 2027 revenue menu, lawmakers were interested last year and partners expect a bill this year – election results will determine whether there is a sympathetic governor.
- Finally, Washington DC lawmakers discussed it and may pursue it in the future as council chair seeks new revenue solutions. The new mayor is more receptive than the outgoing one.
In addition to the places discussed, bills were also introduced in Hawaii, Rhode Island, and Virginia. We tracked relevant media attention in DC, Virginia, Rhode Island, Vermont and partner briefs or blogs in Oregon, DC, Virginia, New Jersey, New York, Hawaii, Maine, New Mexico and West Virginia. ITEP will release a new state Wealth Proceeds Tax report with updated fiscal numbers in time for the 2027 state legislative sessions. Several of our policy priorities moved in states in 2026, leaving us well poised to make progress on this crucial innovation in 2027.
Learn More
- Paper: Wealth Proceeds Tax: How Oregon Can Tax Income from Wealth
- Report: Virginia Can Raise $992 million with New Wealth Proceeds Tax
- Article: A D.C. Wealth Tax Could Provide Relief for Black Residents
Contact
For more information, contact Amy Hanauer, Executive Director, amy@itep.org.
New Practice Lab at New America
Automatically returning money owed to families missing out on tax credits.
About the Innovation
Colorado’s proactive tax-refund pilot uses existing GenTax software—which is used by more than half of U.S. states—to identify and return unclaimed tax credits to low-income families who have overpaid or missed out because of filing complexities, lack of awareness, or fear. The innovation flips the traditional enforcement paradigm by using tax-department technology to find people who are owed money, rather than only identifying underpayments. New Practice Lab is working to build the evidence base from the Colorado pilot and help other states learn from and adopt this approach.
Six-Month Update
Colorado has embedded this model of identifying individuals owed tax credits into their annual workflow and is just kicking off their second year of this effort. Governor Polis will also be hosting a press event in September to discuss the success of this effort. The pilot to support pre-filled tax returns ended in June with promising results – about 5,400 filers signed and accepted the prefilled return (which accounted for 36% of the letter recipients), distributing about $2.6 million.
A number of additional states (up to eight states) have expressed interest in adopting this program, and we are talking to a few states about implementing this effort in 2027.
The Colorado Department of Revenue and Governor’s Office teams have showcased this effort to academics, policymakers, other state Governor’s office staff teams, peer tax administrators and technology teams as they continue to share thought leadership. States currently working through their work plans for the upcoming years are creating scope to explore the possibility of streamlining and simplifying tax filing for their residents. State interest is growing, while state capacity, funding and resource constraints remain the primary hurdles.
Learn More
Contact
For more information, contact Simone Brody, Senior Advisor, brody@newamerica.org.
Niskanen Center
Reviving America’s contributory tradition by expanding payroll taxes as a foundation for public benefits.
About the Innovation
The American welfare state’s most generous and accessible programs—including Social Security Disability Insurance, Medicare, and Unemployment Insurance—are built on a contributory social insurance model financed by payroll taxes. While payroll taxes are sometimes viewed as less equitable than progressive income taxes, they are progressive on net by redistributing resources to those unable to work due to age, health, disability, or temporary circumstances. This approach has proven politically resilient, as seen in the recent expansion of state-level paid leave in 13 states. However, paid leave’s contributory model is facing new threats and many state unemployment insurance programs are built on weak fiscal foundations. Niskanen Center seeks to secure consensus around contributory finance through evidence building, outreach, and coalition building.
Six-Month Update
The Niskanen Center continues to focus on the fundamental importance of having a broad taxable wage base to fund unemployment insurance at the federal and state levels. We anticipate delving more into the issues of experience rating and employee-side taxes next year.
Our new policy analyst has supercharged our ability to extend this work to paid family and medical leave. This includes several new explainers on the importance of safeguarding its contributory structure and a purple/red state-friendly model bill for paid leave that keeps payroll taxes at its core. We are also planning for several “big think” pieces on the broader role of payroll taxes in funding social policy, including where we should and should not rely on them.
Learn More
- Commentary: How Alaska’s Unemployment Insurance System Can Pave the Path to Paid Parental Leave
- Commentary: Growing the Base: Kansas Cultivates a More Resilient UI System
- Report: How Taxable Wage Base Reforms Can Strengthen Unemployment Program Solvency
Contact
For more information, contact Josh McCabe, Director of Social Policy, jmccabe@niskanencenter.org.
Tax Law Center at NYU Law
Remaking federal tax administration.
About the Innovation
The Tax Law Center at NYU Law is creating an executable vision for rebuilding and remaking the federal tax administration system. This builds and expands on prior plans to modernize the IRS and addresses damage from IRS degradation and threats to taxpayer privacy. The project will develop plans to strengthen legal structures, improve funding mechanisms, address regulatory and litigation processes, and measure and reduce both the tax gap and the credits uptake gap. The Tax Law Center will lead key aspects of defending the rule of law within the tax system, maintain institutional knowledge, develop blueprints for rebuilding tax administration in a future administration, and socialize these efforts with stakeholders to ensure alignment on priorities when there is an opportunity to act.
Six-Month Update
The Tax Law Center has created, socialized, and published new introductory resources on why federal tax administration matters, and key priorities in remaking it. Additional new resources will launch in Fall of 2026 intended to support a broad range of stakeholders to understand and engage with remaking federal tax administration.
Learn More
- Blog: Why We Should Modernize the IRS—and Where to Start
- Explainer: Resources on the Trump IRS Lawsuit and Settlement Agreement
- Project: The Federal Tax System Explained
Contact
For more information, contact Richard Chen, Director of Operations and Strategy, rich.chen@nyu.edu.
Washington Center for Equitable Growth
Reclassifying large pass-through businesses to strengthen equitable revenue systems.
About the Innovation
Requiring large pass-through entities (partnerships and S-corporations) to file as C-corporations will help eliminate tax avoidance schemes like the carried interest loophole and payroll tax dodges. To complement this change, the corporate tax rate should rise to a level that balances competitiveness with fiscal sustainability. Together, these reforms would enhance administrative efficiency, replace costly arbitrage with consistent investment incentives, and ensure wealthy individuals disguised as “small business owners” pay their fair share. Evidence from Treasury, Congressional Budget Office, and independent economists shows that income shifting through pass-throughs has driven declining effective tax rates among the top 1%. Simplifying entity taxation is one of the most cost-effective ways to raise revenue and restore progressivity without dampening investment. Washington Center for Equitable Growth aims to transform this concept into a fully developed, actionable policy proposal through a combination of technical analysis and coalition building.
Six-Month Update
There’s been a lot of activity in the pass-through tax arena since the Showcase in March! Equitable Growth hosted a two-day private convening on the topic in May, helping to build consensus among advocates, policymakers, funders, academics, and think tankers that action is needed. Soon thereafter, new concrete proposals were floated by allies – citing Equitable Growth’s work – and a new book from leading economic researchers in Equitable Growth’s network is coming out in September. Equitable Growth has also published new content in this area and is currently considering a webinar for state and federal advocates that would provide poll-tested guidance on how to message against the claim that closing pass-through loopholes amount to a tax increase on “small business”.
Learn More
- Article: Cracking Down on Pass-Throughs
- Policy Proposal: Toward a Uniform Business Tax System
- Report: The Other Two-Tiered U.S. Tax System
Contact
For more information, contact David Mitchell, Senior Fellow, dmitchell@equitablegrowth.org.
The innovations included in the Ideas Showcase and this update are intended to spark dialogue and support funder learning. Inclusion does not constitute an endorsement by Economic Opportunity Funders or the Tax Equity Funders Network.